Best Ways to Use Insurance for RECO Immersive in 2026
If you are staring at an insurance card and feeling stuck, that reaction makes sense. The card looks simple, but treatment coverage rarely is. Many families in Delray Beach call because they are worried care will be delayed, denied, or too costly to start. The good news is that insurance often helps more than people […]
If you are staring at an insurance card and feeling stuck, that reaction makes sense. The card looks simple, but treatment coverage rarely is. Many families in Delray Beach call because they are worried care will be delayed, denied, or too costly to start. The good news is that insurance often helps more than people expect once the details are checked carefully.
What people often misunderstand about insurance and treatment coverage
Why a benefits card can hide more than it reveals about rehab coverage
A benefits card is only a summary. It rarely tells you the full story about behavioral health benefits, substance use disorder coverage, or limits tied to insurance verification for Delray Beach rehab. The real policy language may separate mental health insurance benefits from addiction treatment insurance coverage, and that difference changes everything. The front of the card is not the same as the plan rules.
We hear this from families every week. They assume the card tells them whether Delray Beach rehab is covered, but it often does not show visit limits, pre-approval rules, or network rules. That is why Florida rehab insurance questions should start with verification, not guesswork. A quick review can clarify whether the plan helps with detox, residential treatment facility care, or outpatient program Delray Beach services.
The difference between behavioral health benefits and substance use disorder coverage
Behavioral health benefits can include therapy for anxiety, depression, or bipolar disorder therapy. Substance use disorder coverage may apply to alcoholism treatment center care, opioid rehab Delray, cocaine detox Florida, or prescription pill addiction treatment. Those are related, but they are not always handled the same way by insurers. That is especially true when someone needs dual diagnosis treatment for co-occurring disorders.
One client in Palm Beach County had coverage for weekly therapy but not for the level of structure needed after fentanyl treatment. The plan covered mental health therapy, yet the addiction side needed a separate review. Once the team checked the policy, the family learned the plan did support a higher level of care with prior authorization. That changed the timeline in a real way.
Why out-of-network is not the same thing as out of options for Delray Beach rehab
People hear out-of-network benefits and think “no coverage.” That is not always true. Many PPO plans still help with private rehab insurance options, even if the facility is not in network. The real question is how much the plan pays, what the deductible is, and whether the provider can verify benefits before admission.
This matters in South Florida recovery settings, where families often compare Delray Beach rehab, Boca Raton outpatient, and West Palm Beach mental health options. Out-of-network may still be the right fit if the clinical match is stronger. For some people, the right environment matters as much as the dollar amount. A coastal healing environment can help a person stay engaged when treatment feels hard.
When a quick insurance check matters more than comparing treatment brochures
Brochures sound polished. Coverage rules do not. If someone is in withdrawal, unsafe, or drifting deeper into alcohol or drug use, the fastest useful move is often insurance verification. The admissions team can compare benefits against the needed level of care instead of leaving you to decode small print alone.
On the projects we have seen this year, the families who waited to compare glossy materials often lost time. The families who asked about insurance verification for Florida rehabs in 2026 got clearer answers faster. That matters when you are looking at South Florida detox coverage, inpatient rehab Palm Beach County options, or a mental health IOP. In a crisis, clarity beats perfect research.
The paper trail that turns a confusing policy into usable care
What insurance verification actually checks before admission
Verification is not a sales call. It is a practical review of your plan’s rules. The team checks whether the policy covers detox services, partial hospitalization program care, intensive outpatient, family therapy, and sometimes medication-assisted treatment. They also look for exclusions tied to alcohol, benzodiazepine withdrawal, or dual diagnosis treatment.
A strong verification also checks network status and plan type. That means looking at Aetna rehab coverage, Cigna rehab coverage, or Blue Cross Blue Shield rehab coverage with the same care you would use for any medical decision. It can also clarify whether the plan supports admissions process for private rehab in Delray Beach steps, or whether self-pay options may be smarter for part of care. The goal is simple: no surprises at intake.
How prior authorization changes the path for detox, PHP, and intensive outpatient
Prior authorization for rehab means the insurer wants approval before paying for certain levels of care. That is common for detox, PHP, and intensive outpatient. It can also affect how quickly a person enters care. If the paperwork is missing, care can stall even when the clinical need is obvious.
This is why timing matters. If someone needs South Florida detox, the approval process should begin right away. The same applies to levels of care for detox, PHP, and intensive outpatient, because each level uses different billing codes and medical rules. A rushed but accurate authorization request can help avoid delays when withdrawal risk is high or when relapse prevention must start now.
Which questions to ask about Aetna, Cigna, and Blue Cross Blue Shield benefits
Ask direct questions. Do not settle for a vague “it should be covered.” Ask whether the plan covers inpatient rehab Palm Beach County services, what the deductible is, and whether the claim needs prior authorization. Also ask whether the policy supports co-occurring disorders and dual diagnosis, since that often changes the care path.
Useful questions include:
- Is detox covered first, or must I start at PHP?
- Does the plan cover medication-assisted treatment, including Suboxone maintenance or Vivitrol injections?
- Are trauma therapy South Florida services covered if PTSD is involved?
- Does family therapy count under behavioral health benefits?
- What happens if the facility is out of network?
Those answers help you compare plans without getting lost in jargon. They also make accreditations and licensed treatment standards easier to evaluate, because coverage and quality should work together.
How deductible, coinsurance, and out-of-pocket max shape private rehab decisions
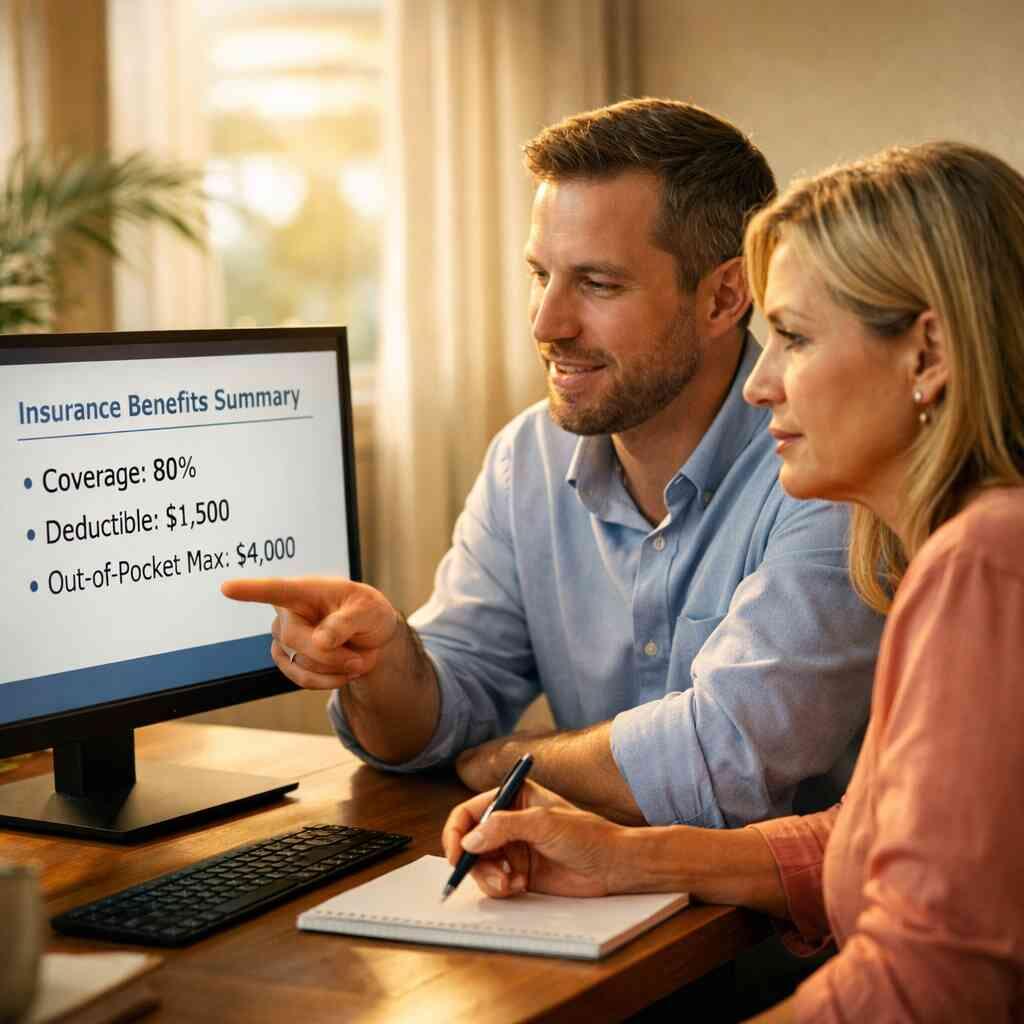
Deductible, coinsurance, and out-of-pocket maximum are the three numbers that shape cost. The deductible is what you pay before the plan starts sharing costs. Coinsurance is the percentage you pay after that. The out-of-pocket max is the cap that limits what you spend in a covered period.
TermWhat it meansWhy it mattersDeductibleAmount you pay firstCan affect how fast coverage startsCoinsuranceShared cost after deductibleChanges your weekly billOut-of-pocket maxYour yearly capProtects you from runaway costsFamilies often ask about private rehab because they fear the bill more than the treatment itself. That fear is understandable. Yet sometimes the deductible has already been met, or the out-of-pocket max is close. In those cases, insurance for rehab in Delray Beach can help more than expected, especially for longer care plans that include aftercare support.
When self-pay can still make sense even if insurance is active
Insurance is not always the cheapest path. If the plan has a very high deductible, a narrow network, or weak out-of-network benefits, self-pay may be cleaner. That can be true for a short stabilization stay, a specific therapy track, or a fast admission when waiting on approval feels risky. Sometimes speed has value.
The key is to compare the total picture, not just the premium. Self-pay can also help when someone wants privacy, needs a narrow clinical fit, or is using a plan with confusing exclusions. It is still wise to verify the claim path first, because even active insurance may cover more than you think. A brief review can keep you from paying twice.
Where coverage and clinical need meet inside a South Florida treatment plan
Why dual diagnosis treatment often needs a different coverage review than single-issue care
Dual diagnosis treatment means a person has a substance use disorder and a mental health condition at the same time. That may include depression and addiction, anxiety treatment, bipolar disorder therapy, or PTSD treatment. This is not rare. NIDA and SAMHSA both support the co-occurring disorder model, which treats both conditions together instead of splitting them apart.
Insurance often reviews these cases differently. A policy may cover therapy for depression but require separate authorization for detox or residential treatment facility care. That is why co-occurring disorders and dual diagnosis care deserve a deeper benefits check. For many people, the right review can open access to evidence-based treatment instead of forcing a false choice between mental health and addiction care.
How insurance may apply to detox services, medication-assisted treatment, and relapse prevention
Insurance can help with cocaine detox Florida coverage, opioid rehab insurance, fentanyl treatment coverage, heroin recovery, and benzodiazepine withdrawal treatment coverage. It may also support medication-assisted treatment coverage, such as Suboxone maintenance or Vivitrol injections. These FDA-approved medications are often part of a larger plan, not a shortcut. They work best with therapy, monitoring, and relapse prevention. 
Here is a simple rule. If withdrawal is dangerous, detox comes first. If cravings remain strong, medication support may help. If triggers and routines drive relapse, therapy and coping skills matter. Insurance may cover each piece differently, so the plan has to be checked line by line. For more on mental health therapy and behavioral health benefits, the coverage review should also include sessions tied to trauma, mood, and stress.
What to know about PHP versus IOP when choosing an outpatient program in Delray Beach
PHP and IOP are not the same. A partial hospitalization program usually gives more hours of treatment each week. Intensive outpatient gives fewer hours, but still offers structure, groups, and clinical support. The right choice depends on your symptoms, home setting, work demands, and safety needs.
If you want a deeper comparison, how PHP and IOP compare in Palm Beach County is the sort of question insurance should answer alongside the clinical team. In Delray Beach, an outpatient program may fit someone who can sleep safely at home but still needs daily support. A mental health IOP often works well for people leaving detox or stepping down from residential care. Coverage should match that level of structure.
Which therapies are often tied to evidence-based care such as CBT, DBT, EMDR, and family therapy
Insurance reviewers look closely at evidence-based treatment. That means approaches backed by research, not just tradition. Cognitive behavioral therapy helps people spot thought patterns that fuel use. Dialectical behavior therapy helps with emotion regulation and distress tolerance. EMDR trauma therapy can support PTSD treatment when trauma is part of the story.
Family therapy matters too. Many plans cover it when the clinical need is clear, especially in addiction treatment insurance coverage. To see how these services fit together, CBT, DBT, and EMDR therapy for trauma and addiction can help explain the clinical side. The same goes for family therapy coverage for recovery support, which can improve communication and reduce relapse pressure at home.
How coverage may extend to aftercare planning, sober living resources, and alumni support
Recovery does not end at discharge. Good plans often include aftercare planning, case management, life skills training, and relapse prevention support. Some policies may also support sober living resources or alumni program contact, though coverage varies a lot. The point is continuity, not a hard stop.
One person leaving residential treatment recently needed help with vocational support and nutritional counseling, not just group therapy activities. Insurance covered part of the transition support because the treatment team documented clinical need. That kind of planning can make the move from structured care to daily life far steadier. RECO Health Network for integrated recovery care reflects that broader model of continuing support.
Why local recovery settings in Delray Beach, Palm Beach County, and nearby South Florida can matter to families
Location matters more than people think. Delray Beach has a strong recovery community, and that can make a real difference during vulnerable weeks. The area near Atlantic Avenue, the beach, and nearby nature preserves gives people a calm setting without feeling isolated. Families in Palm Beach County often want that balance.
Local access also helps with logistics. A person from Fort Lauderdale detox or Miami addiction help may need a plan that fits travel, work, and family needs. Someone in Boca Raton outpatient care may want to stay close enough for family weekend visits. When the setting is right, treatment feels more usable, not just more impressive on paper.
The next move that keeps treatment possible instead of stalled
How to gather the documents and details that speed up admissions
Keep it simple. Gather the insurance card, a photo ID, medication list, and any recent discharge paperwork. If there has been a recent ER visit, detox stay, or psychiatric admission, bring that too. Those details help the admissions team understand risk and level of care.
It also helps to write down symptoms in plain language. Note signs of addiction, sleep issues, panic, cravings, blackouts, or withdrawal symptoms. If there is trauma, mention that. If there is a family history, mention that too. This makes the intake process faster and more accurate, especially when the team is checking insurance for outpatient program Delray Beach options or higher levels of care.
When to ask for a case concierge review of benefits and level of care
Ask for help as soon as you feel stuck. If the policy language is confusing, a case concierge review can compare benefits with the right level of care. That matters when someone may need what to expect from a mental health IOP in South Florida, or when residential treatment is more appropriate than outpatient care.
A concierge-style review is useful when the family feels pressure, fear, and time running out. It can also help if you are weighing beachside recovery against staying near home. The goal is to match the person to the right support, not the loudest brochure. Good admissions work feels calm, not rushed.
How to spot gaps in coverage before they become delays in treatment
Watch for red flags. If the plan excludes detox, caps therapy visits, or requires repeated authorizations, those are real barriers. If the network is narrow, ask what out-of-network benefits exist. If the plan covers mental health but not substance use care, that needs clarification before admission.
A useful checklist:
- Confirm network status.
- Ask about prior authorization for rehab.
- Ask whether PHP and IOP are both covered.
- Ask how medication-assisted treatment is billed.
- Ask what happens after discharge.
That list can prevent a stalled admission. It can also help you compare Florida rehabs that take insurance without guessing which one fits the policy best.
What to do if your plan is thin but the need for care is urgent
Do not wait for perfect coverage if the need is urgent. If someone is at risk, start with the fastest safe option. That may mean detox, a residential treatment facility, or a partial hospitalization program. If the plan is thin, self-pay options can bridge the gap while benefits are clarified.
This is where a direct conversation helps. Ask the team what can start now and what can wait. Ask whether a step-down path is possible, such as moving from detox to PHP to intensive outpatient. That sequence can protect safety while managing cost. Learning new skills takes time and practice, and care should not stop because a policy is messy.
How to use a verification call to turn insurance questions into a real treatment decision
A verification call should end with clarity. You should know whether the plan covers treatment, what level it supports, and what your likely cost range is. You should also know whether the path is in network, out of network, or partly self-pay. That information turns fear into action.
If you want to see how this works in practice, a verification call can pair with a look at the guide to insurance verification for Florida rehabs in 2026 process. It can also help you decide whether RECO Immersive’s location at 140 NE 4th Avenue, Delray Beach, FL 33483 fits the clinical and financial picture. If you are comparing private rehab, outpatient support, or a full start in Delray Beach, make the call today and ask for a benefits review. You do not have to sort every detail alone, and you do not need every answer before reaching out.
Frequently Asked Questions
How long does detox last at a Delray Beach rehab?
Detox length depends on the substance, health history, and withdrawal risk. Alcohol and benzodiazepine withdrawal can require close medical monitoring. Opioid withdrawal may look different and may respond well to medication support. A clinician should review the person’s symptoms before giving a timeline. Insurance often covers detox when medical necessity is documented.
Does RECO Immersive take my insurance?
The fastest way to find out is through insurance verification. Coverage depends on your plan, network, deductible, and required authorizations. Many Florida rehabs that take insurance still need a benefits review before admission. RECO Immersive can help you understand whether your plan applies to detox, PHP, IOP, or dual diagnosis treatment.
What is PHP vs IOP?
PHP, or partial hospitalization program, offers more hours and structure than IOP. Intensive outpatient gives strong support with fewer weekly hours. PHP often fits people who need daily stabilization. IOP may fit people stepping down from a higher level of care. The right choice depends on safety, symptoms, and home support.
Can insurance cover trauma therapy and PTSD treatment?
Yes, many plans cover trauma therapy when it is part of a behavioral health treatment plan. That may include CBT, DBT, or EMDR trauma therapy. Coverage can vary based on diagnosis, provider type, and plan rules. A verification call can clarify whether trauma work is included under mental health benefits.
What if I need help for depression but not addiction?
That still matters. Depression, anxiety, and bipolar disorder therapy can be covered under behavioral health benefits even without substance use treatment. If addiction is also present, dual diagnosis treatment may be the better fit. A thorough intake can separate what is urgent from what is secondary. That helps the care plan match your actual needs.
Can family be involved in treatment?
Often, yes. Family therapy can support communication, accountability, and relapse prevention. Some plans cover family sessions when they support the primary treatment plan. This can be especially helpful for young adult rehab, veterans addiction help, and gender-specific treatment settings. Ask whether family weekend or family programming is part of the benefits review.
What should I do today if I think someone needs rehab?
Call for a verification review and gather the insurance card, medication list, and any recent discharge papers. If withdrawal, suicidality, or medical danger is present, seek urgent clinical help right away. If the situation is less acute, ask about detox, residential care, PHP, and IOP in the same call. The goal is to replace uncertainty with a clear plan.